25 tips that change your financial mindset
Author - Mansur Ismagulov
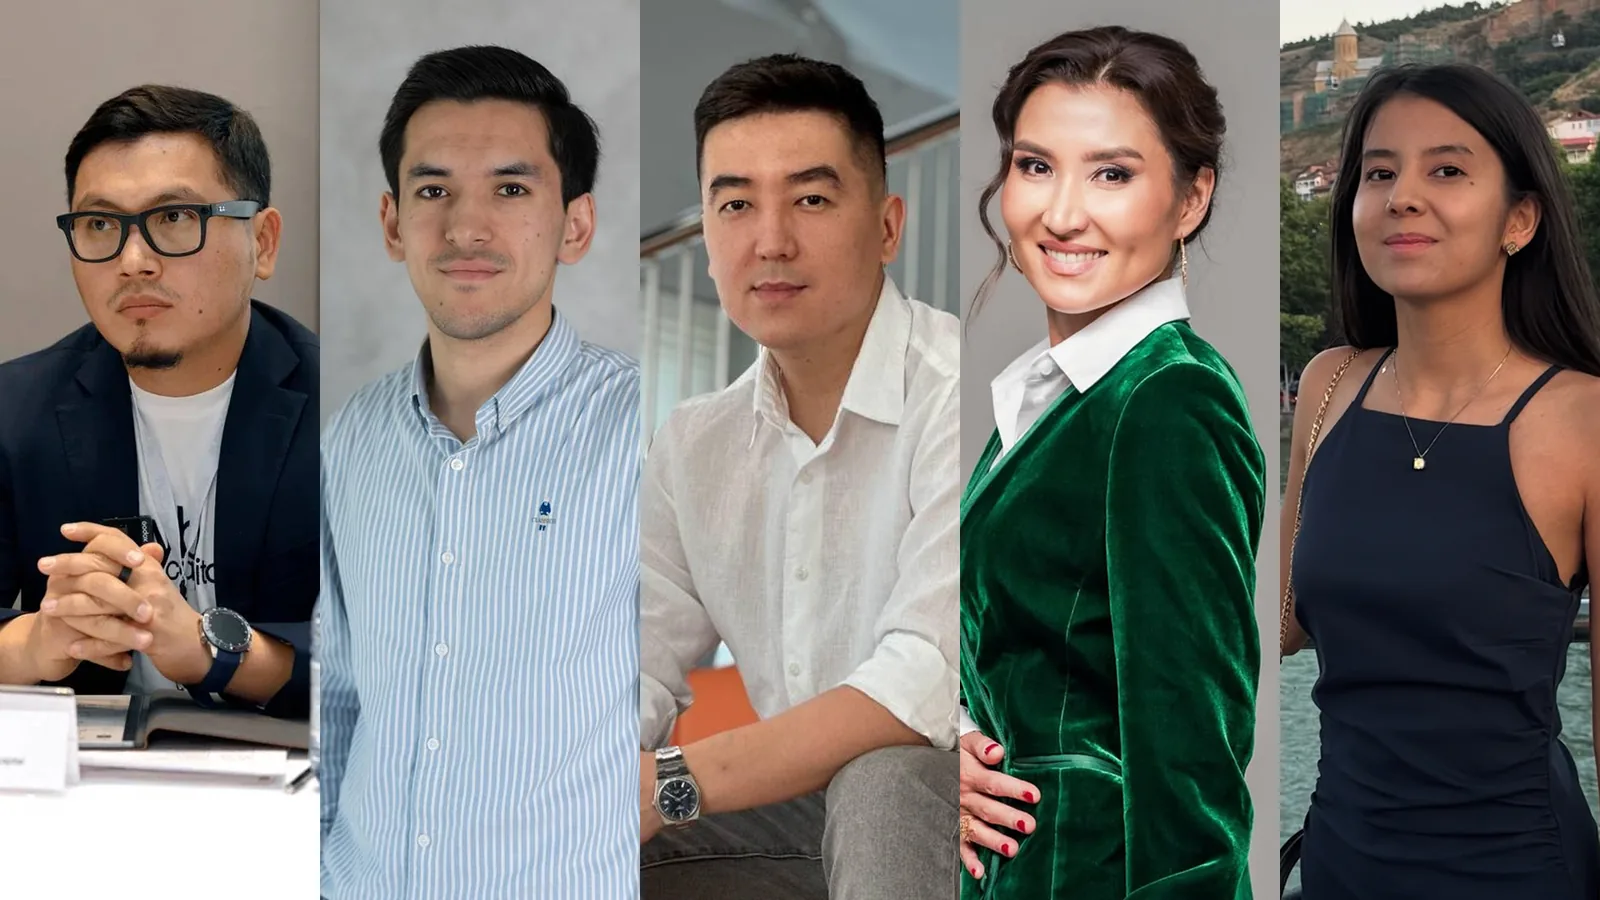
How CEOs and experts handle money, what constitutes their “safety cushion,” why discipline matters more than the amount, and why you should start investing in yourself. We’ve gathered practical advice to help you build a healthy relationship with finances — both in business and in personal life.
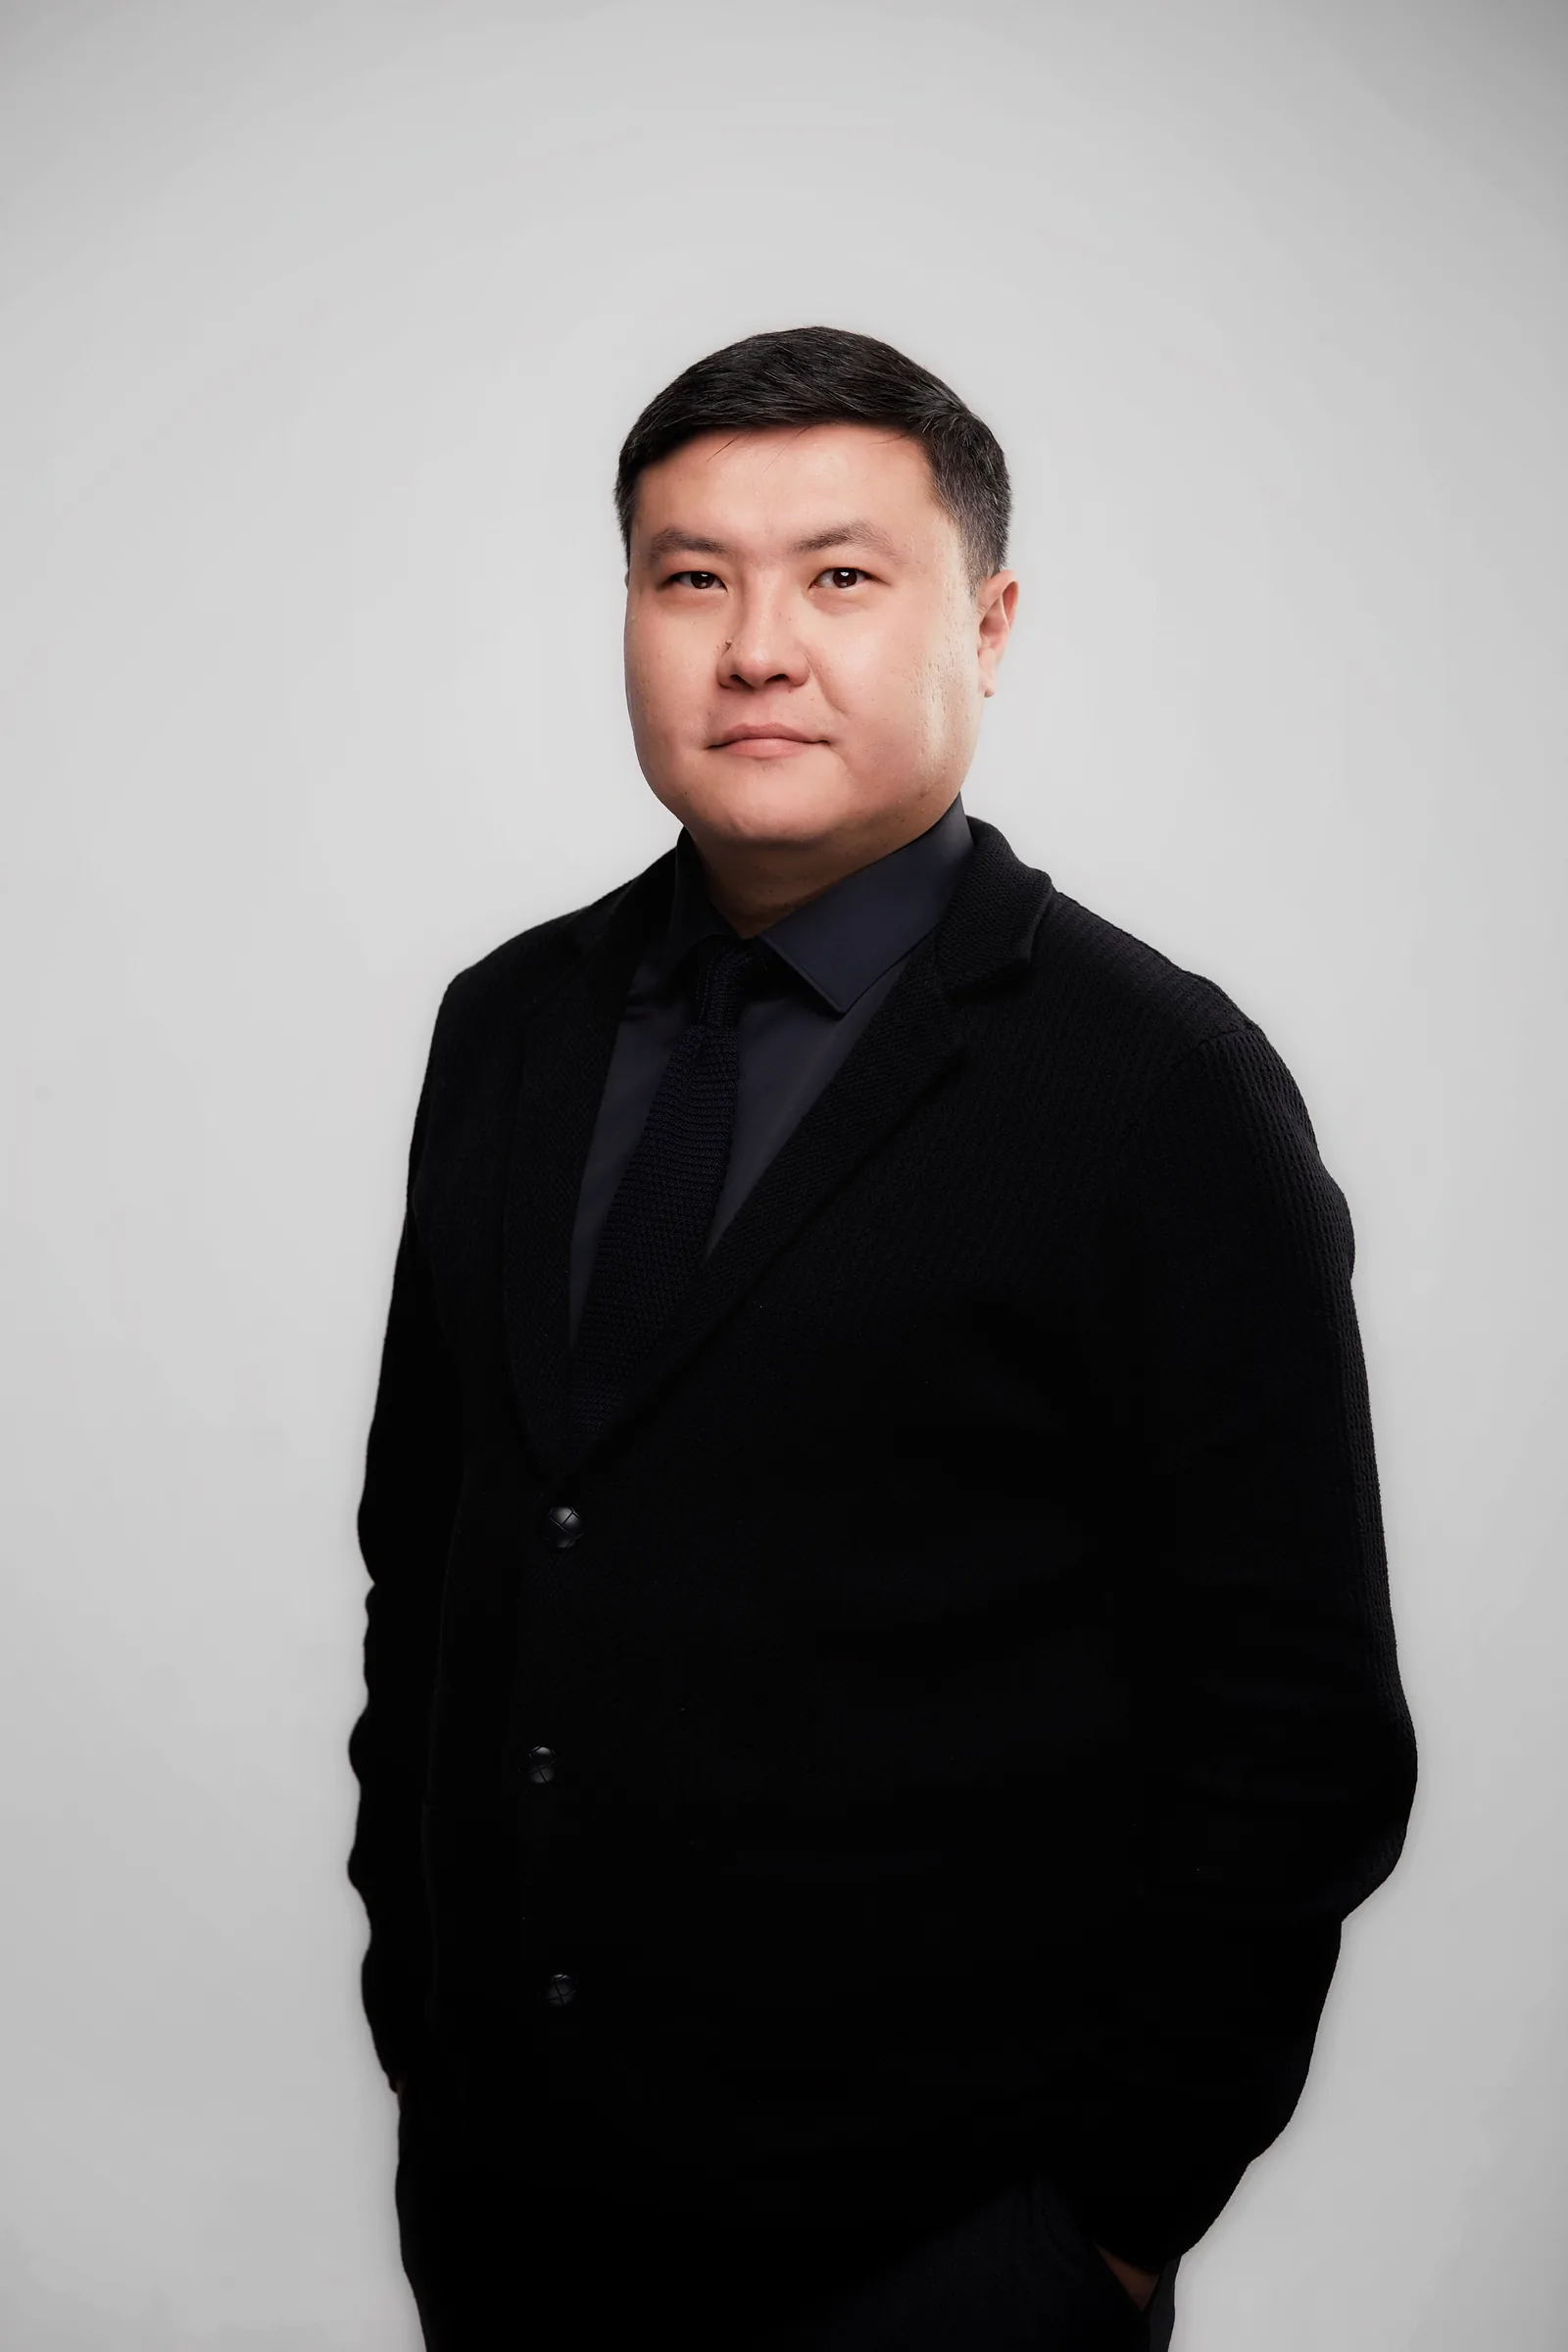
Askar Bilisbekov, Managing Partner, CEO byb capital, Instagram
For the average person who plans their life and aims for success, the most important thing is to develop the habit of learning. To learn regularly and always.
Such a person, most often, has little understanding of what finances are. Therefore, initially, it is necessary to either study independently or take financial literacy courses for beginners. Understand the basics of why we need finances. And the sooner, the better.
After that, study the topic of investing: who and when can start investing, and how much money is required for this.
Read books, starting with Theodore Dreiser’s “The Financier.”
Subscribe to free channels on social media, including news outlets: ft.com, bloomberg news, wsj, HBR.
Alisher Alimov, CEO Azma Finance, Instagram
Before, even before I met my partner Anar @anarkostenko, I managed my finances poorly. Everything was mixed up: personal and business money, there was no clear discipline, and I didn’t understand why management reports were necessary. After we founded @kspconsult, I learned a completely different approach.
For example:
1. Always separate personal and corporate finances.
2. Keep a safety cushion of at least three to six months’ worth of expenses.
3. Look at money not as numbers, but as a tool for growth.
4. Analyze the efficiency of expenses and manage cash flow daily.
5. Do not invest in instruments I don’t understand. Only invest in what I clearly understand.
These habits have become part of me and have helped not only in business but also in personal life.
Daulat Aitmakhanov, Founder and CEO Finflow, Instagram
1. Financial safety cushion — have a reserve equivalent to at least six months of living expenses based on your monthly income. This reduces stress and provides flexibility.
2. Diversify income sources — do not rely on just one source. Have a side hustle.
3. Save and invest 20% of all income as soon as you receive it. Pay yourself first.
Gulnara Amantay, Investment Consultant, CEO UpsaidLab Advisors, resident of the Astana International Financial Centre (AIFC), Instagram
1. Spend less than you earn — this is a basic rule without which no strategy works.
2. Comfort cushion — keep a reserve for six months of living expenses so you don’t have to take loans during a crisis. This is your basic foundation for peace of mind.
3. Money loves discipline. Not chaos, not emotions, not impulses, but a plan.
4. The long-term portfolio is untouchable — it is a tool for the future, not a “wallet for today.”
5. Plan for your child’s education in advance — include it in the family budget, rather than waiting for money to appear on its own.
6. Teach financial literacy to children through family example — they don’t listen, they copy. If you know how to save and invest, they will grow up with that skill.
7. Your money is needed only by you and scammers — therefore, we must understand the matter of money.
8. Financial culture is your responsibility. If you don’t manage your money, someone else will manage it for you.
9. Always save. Even if your income is small — start with 5-10%. It’s the habit that matters, not the amount.
10. Invest in yourself and your mindset — education, skills, and environment shape your income.
Zainab Atabaeva, Investment Manager IT Park Ventures, Instagram
For me, the most important habit is planning expenses and keeping them under control.
I analyze my budget in advance: what expenses are mandatory, and what can be postponed or optimized. It is convenient to do this in a spreadsheet or through apps like Wallet: Budget & Money Manager and CoinKeeper — this makes it much easier to see the full picture and avoid impulsive purchases. For long-term goals, it also helps to forecast future income and expenses: this allows you to optimize cash flows and make more strategic decisions.
The second habit is always to set aside a portion of your income. I have several cards: one for current expenses, and another “inaccessible” one, into which I transfer money immediately after receiving my income. This allows me to gradually build a safety cushion and capital for long-term goals.
In the future, I plan to direct part of my funds toward investments, even with small checks, into stocks or startups, because this is one of the sources of income and valuable experience.
Additionally, I believe it is important to invest in myself: education, new skills, travel. Such investments broaden horizons, create new opportunities, and directly influence how you make decisions and earn money in the future.
My environment also has a strong influence on me: I have many acquaintances who are simultaneously creating additional sources of income — through investments, consulting, freelancing, and education. Their examples motivate me to move in the same direction.
The Tech on Telegram Follow The Tech on Telegram
Keep up with the latest technology and startup news.
Related reading


More from this author
News
zypl.ai begins operations in Japan and focuses on next-generation risk models
Mansur Ismagulov
News
Elon Musk's net worth has exceeded $700 billion for the first time
Mansur Ismagulov
Article Interviews
"Central Asian countries should build a joint ecosystem," — Bekhzod Ismoilov on the development of AI in the region
Mansur Ismagulov
Article Interviews
Bloom's Taxonomy and Engineering Levels: A Practical Growth Model
Mansur Ismagulov
Article Useful
How the IT industry in Azerbaijan developed in 2025: key events
Mansur Ismagulov
News
Tajikistan has become a new member of the regional innovation alliance Central Asian Innovation Hubs.
Mansur Ismagulov