$1 billion in investments and 200 FinTech companies: how the Uzbek market will look by 2030
Not every regulator can say that it has directly participated in creating a new market practically from scratch. When the President's Decree No. PP-359 of November 27, 2025, officially designated the Central Bank of Uzbekistan as the authorized body for FinTech development, it was less the beginning of new work and more an acknowledgment of the path already traveled.
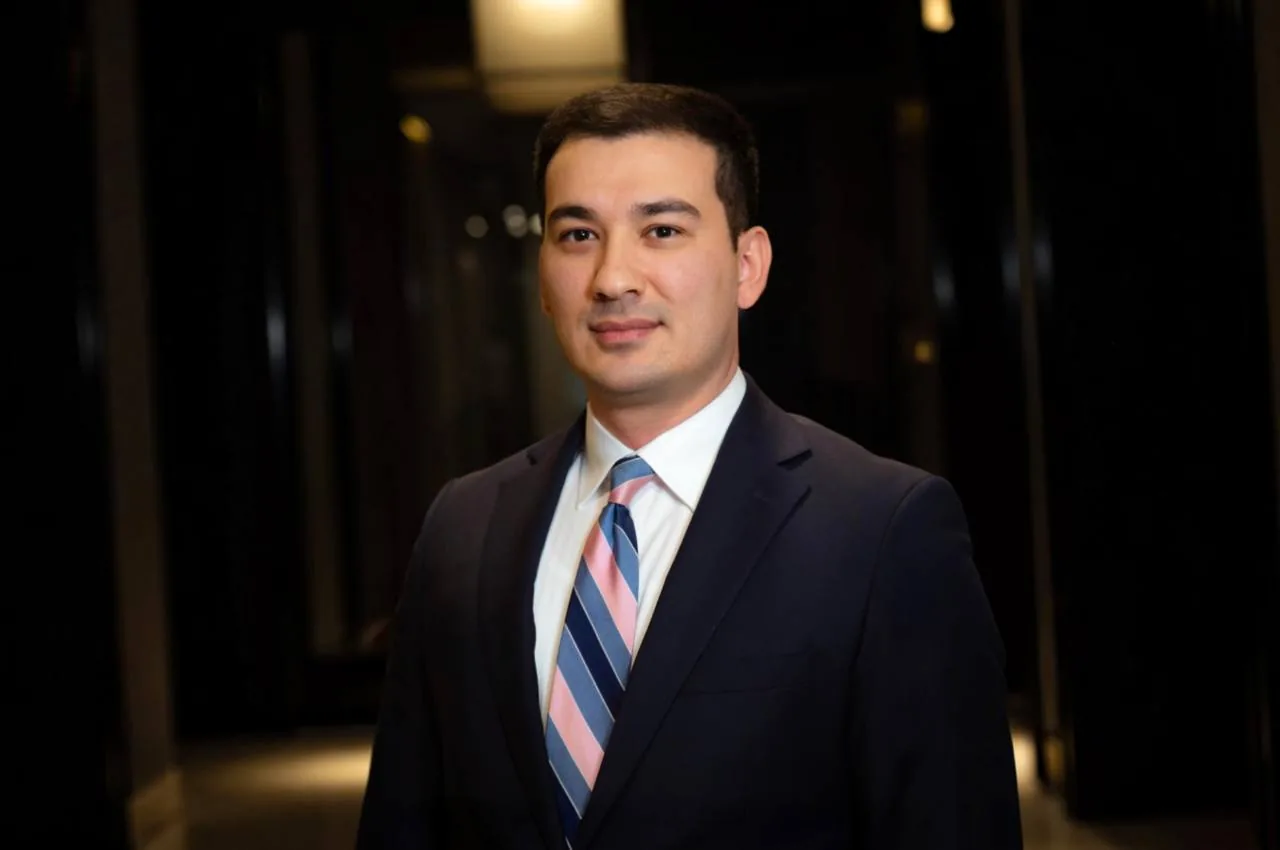
Ravshanbek Kadyrov, who heads the Department of Financial Technology Development at the Central Bank, was one of those who stood at the origins of these transformations: from the creation of a regulatory “sandbox” to the development of the National Strategy for the Development of Financial Technologies until 2030.
We spoke with him about what is currently happening in the financial sector of Uzbekistan, why development is proceeding at such high speeds, and what tasks the country still needs to accomplish.
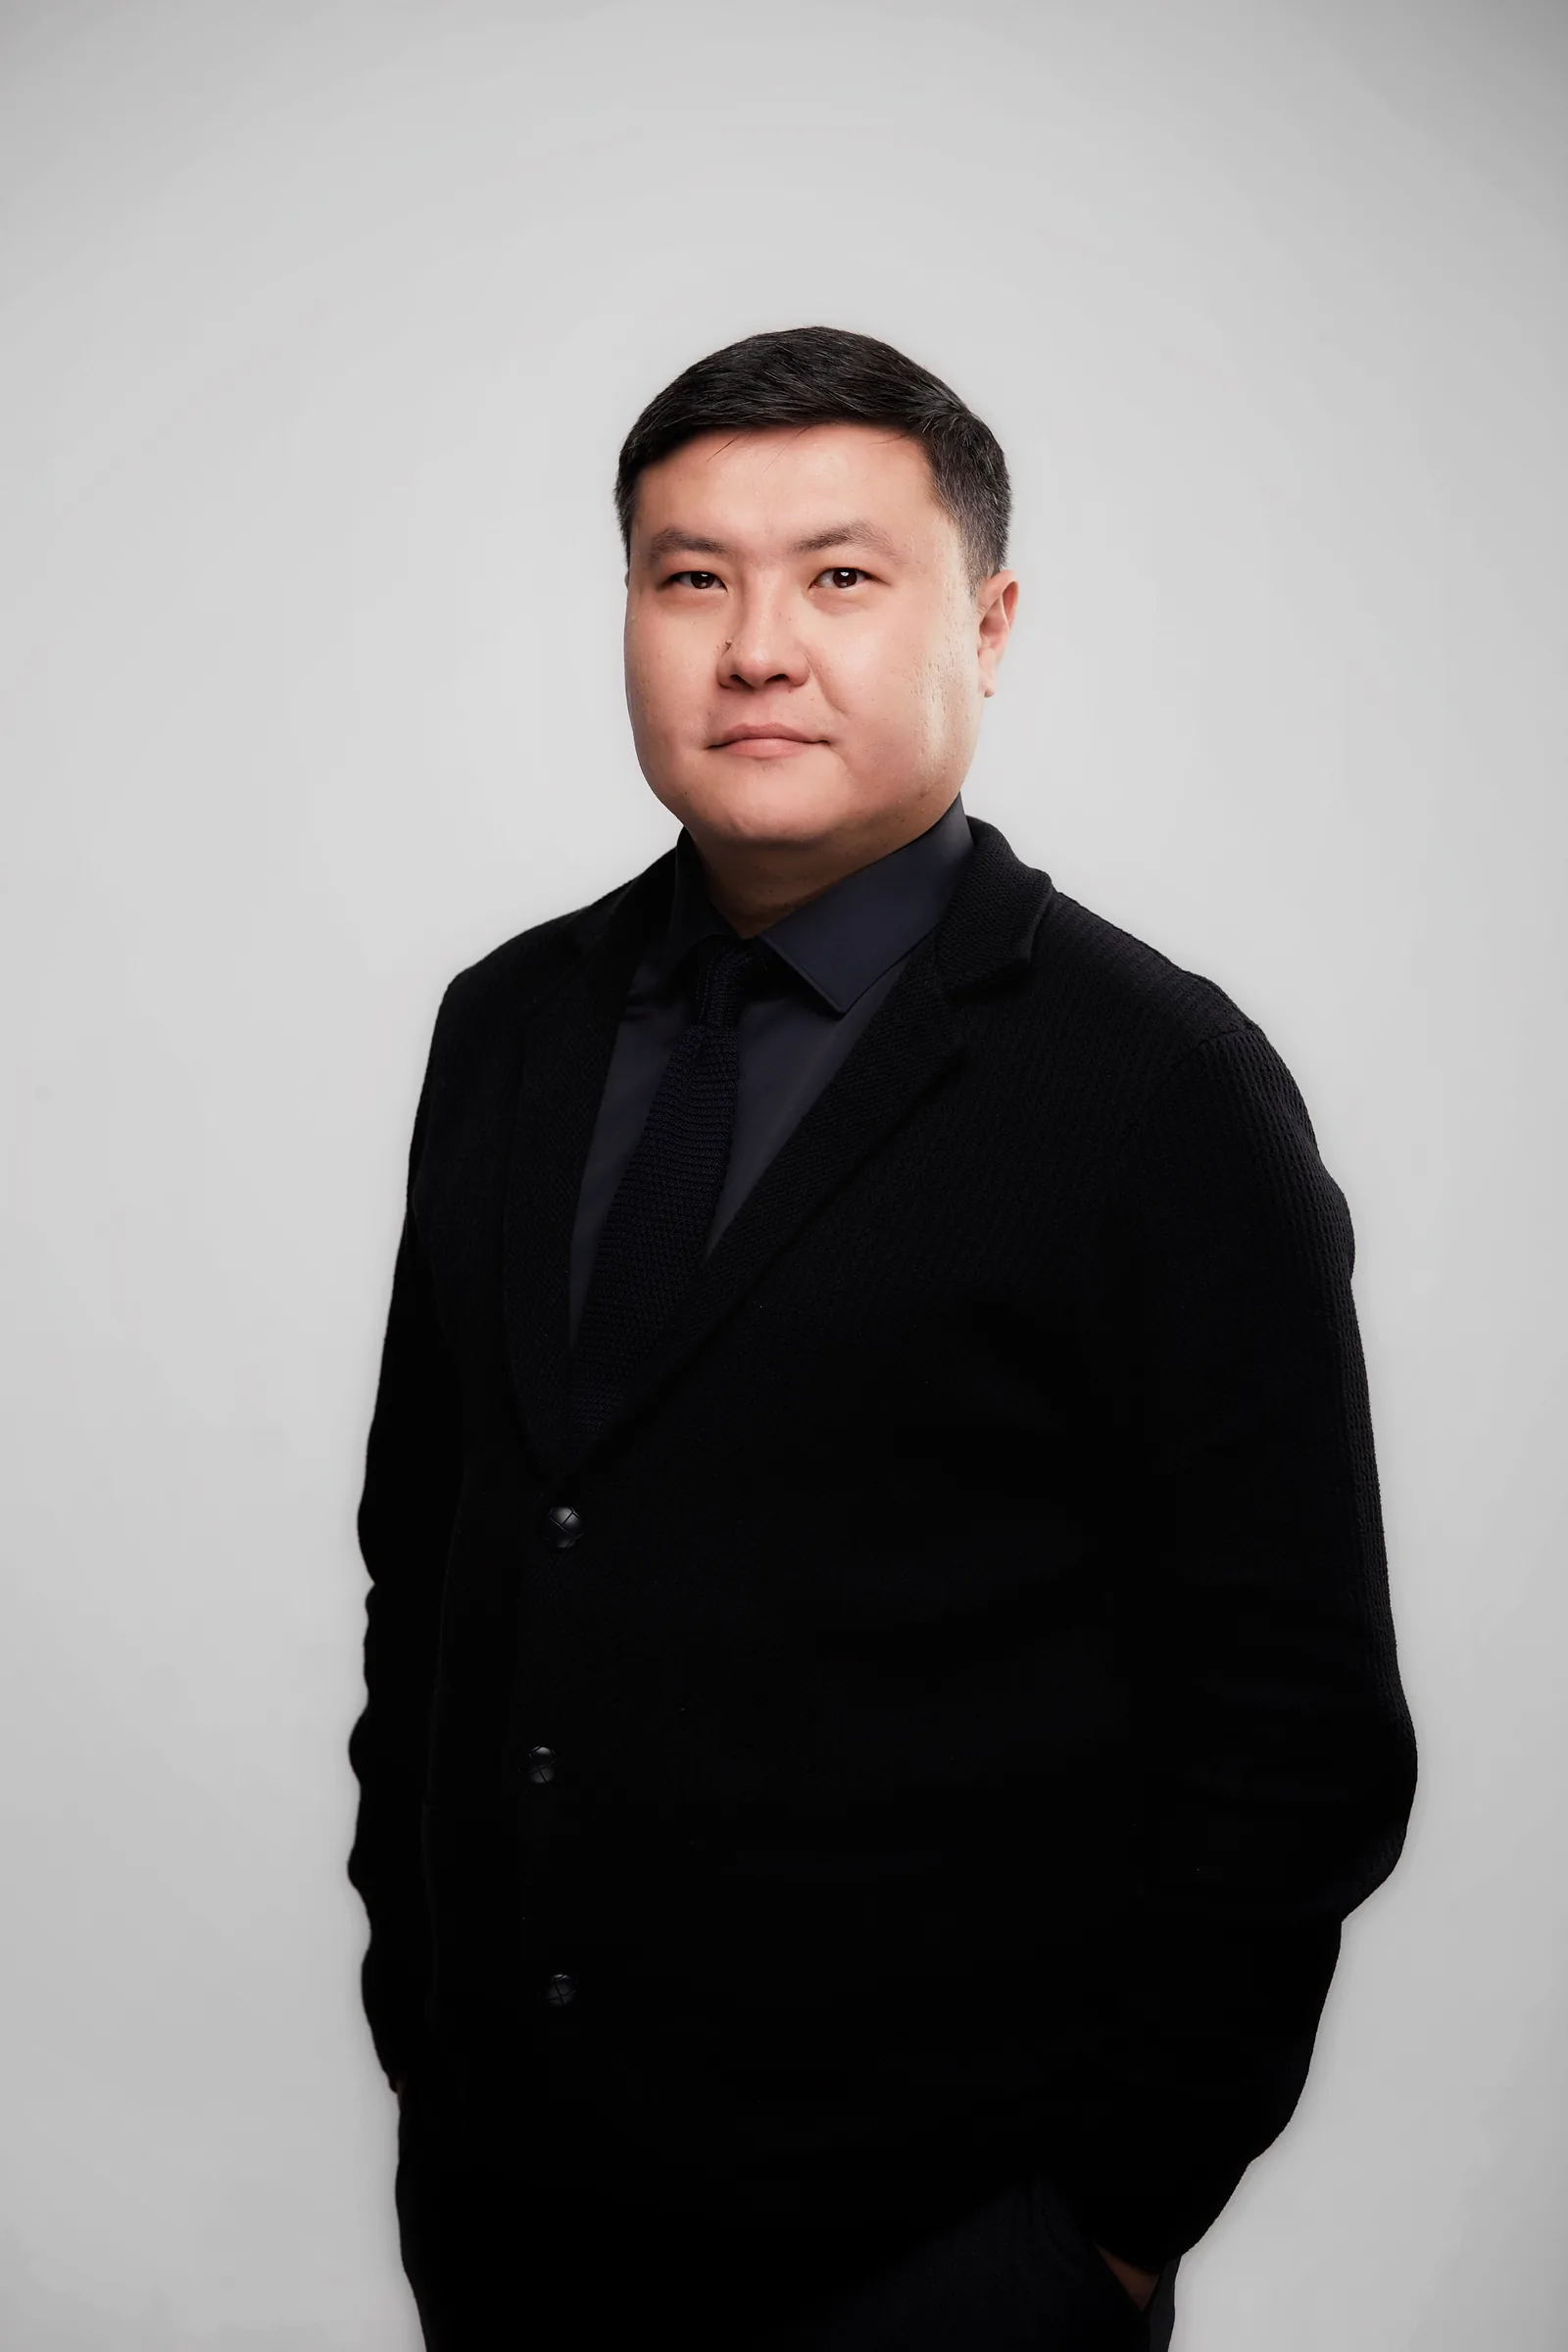
Ravshanbek Kadyrov, city — Tashkent, Head of the Department of Financial Technology Development of the Central Bank of the Republic of Uzbekistan
How Uzbekistan created conditions for the growth of the FinTech market
Currently, the population of Uzbekistan exceeds 37.5 million people. A significant portion of them are young people who actively use smartphones, a group that for many years remained insufficiently served by traditional banking services. This is not just an unmet need — it is a full-fledged market.
When the necessary rules of the game began to take shape — the licensing of electronic money, a regulatory “sandbox,” and standards for the interoperability of digital payments — businesses received clear conditions for launching new products. The growth in the number of companies became a logical consequence of these changes, as the foundation for development already existed.
The main role of the Central Bank was to provide certainty to the market: to establish transparent rules, create clear interaction mechanisms, and send a clear signal that the state views FinTech not as an experiment, but as one of the priority directions for economic development.
Previously, our role was primarily supervisory: we set requirements, issued licenses, and ensured the stability of the financial system. This remains one of the key functions of the Central Bank; however, the new mandate adds another direction — active development of the industry.
Now, the Central Bank is responsible for developing the National Strategy for the Development of Financial Technologies for 2026–2030, creating an Innovation Hub and FinTech Office, as well as launching a venture fund with a volume of $50 million, which will finance early-stage FinTech startups. In addition, we are preparing proposals for improving legislation in cases where the results of the regulatory “sandbox” confirm the possibility of safely scaling new solutions.
But industry development is not only about regulation. We consider it our task to unite market participants. The Central Bank cannot simply wait for the market to form on its own. That is why, already in August of this year, we are jointly hosting the first Silk Road Finance and Technology Forum with the Global Finance and Technology Network.
For us, this is an opportunity to show international partners the direction of the country’s development not through regulatory documents, but through the dialogue we initiate. Our goal is to bridge the gap between innovations and their practical implementation.
About the Silk Road Finance and Technology Forum
The forum will take place from August 24 to 26 in Tashkent across two venues — the Central Asian Expo Uzbekistan and the Center of Islamic Civilization. The program is built around five key areas:
— open banking
— digital assets and stablecoins
— cross-border payments
— Islamic finance
— innovations and investments.
The forum is organized by the Central Bank jointly with the Global Finance and Technology Network, Ant International, the National Agency for Strategic Initiatives, and the Ministry of Digital Technologies.
The main theme of the forum is Unlocking Central Asia's FinTech Value. The concept is based on the idea of “al-jabr” — an Arabic term that gave its name to algebra, as well as a reference to the great scientist Al-Khwarizmi, who was born on the territory of modern-day Uzbekistan.
Forum participants can expect a substantive business program, the opportunity to communicate directly with regulators and government bodies that actually make decisions, and to get acquainted with a market that many international players still underestimate.
How the Instant Payment System reached record volumes
In May 2026, transactions worth more than $12.2 billion were processed through the Instant Payment System in Uzbekistan, and the volume of transactions via POS terminals in the first ten months of 2025 reached 360 trillion sums. These results were made possible by years of developing financial infrastructure.
The Instant Payment System is the result of years of consistent work on developing financial infrastructure.
From the very beginning, we built the system on the principles of full interoperability. This means that payments freely flow between banks and payment organizations without any technological barriers or closed ecosystems. This was a conscious political decision.
In addition, we invested in advance in the development of the QR payment standard. A decree adopted in November 2025 provides for the implementation of a unified QR standard, which should eliminate the remaining fragmentation among various payment service providers.
High transaction volumes are a consequence of the fact that the created infrastructure has earned user trust. People changed their financial habits not because they were told to, but because the system proved to be convenient, reliable, and consistently operational. The figure of $12.2 billion is not a marketing record. It reflects fundamental changes in how residents of Uzbekistan make payments and transfer money on a daily basis.
Why international investors choose Uzbekistan
Investors are looking for a combination of factors rarely found in a single market simultaneously: a large potential audience, still relatively low penetration of financial services, a state that does not create obstacles but, on the contrary, promotes industry development, and a sufficiently transparent regulatory environment that allows for adequate risk assessment. All of this exists in Uzbekistan today. Moreover, the country demonstrates high rates of economic growth. In 2025, the economy grew by 24%, and the volume of remittances from abroad reached $18.9 billion. At the same time, a significant portion of these funds still passes through traditional and relatively expensive channels, opening up wide opportunities for digital financial services.
The demographic factor is no less important. The younger generation is not bound by the habits of traditional banking services and adopts new financial technologies much faster.
The overall investment climate also contributes to the development of FinTech. In 2025, Uzbekistan attracted $43.1 billion in foreign investment, which is 24% more than the previous year. At the recently held Tashkent International Investment Forum, 166 agreements were signed for the same amount — $43.1 billion. One of the key areas of the forum was the development of the Tashkent International Financial Center, which is expected to offer special conditions for FinTech and green financing using English law principles.
This is an important signal for investors: Uzbekistan is not just open to capital; the country is creating an institutional environment that will allow it to retain this capital and use it effectively.
By 2030, we expect to increase the total volume of direct foreign investment in FinTech to $1 billion, and the number of FinTech companies — from 103 to 200.
How Uzbekistan is implementing open banking, CBDC, and digital assets
Uzbekistan is consistently developing several areas of financial technology simultaneously — open banking, the digital sum — CBDC, digital assets, and blockchain solutions for payments. This approach requires clear prioritization and phased implementation.
We are not trying to launch all initiatives simultaneously. The open banking infrastructure, which will ensure secure data exchange via API between banks, payment organizations, and FinTech companies, is scheduled to become operational by September 2026.
The development of a roadmap for the implementation of the digital sum is proceeding as a separate track. We are carefully evaluating what role the central bank digital currency should play alongside existing payment instruments, rather than instead of them.
As for stablecoins, together with the National Agency for Strategic Initiatives, we are currently determining the conditions for their testing within the regulatory “sandbox” before making decisions on broader implementation. The “sandbox” itself was created precisely so that new technologies can undergo testing in a controlled environment before interacting with the entire financial system.
Our confidence is also bolstered by the fact that we are not working in isolation. We have carefully studied the experience of the Monetary Authority of Singapore and engaged international consultants to prepare the National Strategy for the Development of Financial Technologies for 2026–2030.
Strengths of Uzbekistan's FinTech ecosystem
Uzbekistan is developing FinTech according to its own model, betting on the scale of the domestic market, consistent reforms, and active state support.
Kazakhstan has created an impressive international financial center, and we hold in high regard what the International Financial Center “Astana” has achieved. But I do not believe that there is a zero-sum game between us.
The main advantage of Uzbekistan is the combination of the scale of the domestic market and the consistency of the reforms being implemented. Today, the country’s population exceeds 37.5 million people and continues to grow.
If you look at the development of the regulatory “sandbox,” which has been operating since 2022, the high level of integration of state digital platforms with private FinTech services, the mechanisms for co-financing startups within the Digital Startup Program, and the fact that FinTech development issues are considered directly at the level of the President, with the Central Bank designated as the main coordinator of this work, it becomes obvious that we are talking about a level of state support that is difficult to replicate quickly.
At the same time, our task is not to become a copy of the International Financial Center “Astana.” We are building a strong domestic financial ecosystem that will simultaneously be attractive to regional and international partners. These are different development models, and they imply different strategic decisions.
What FinTech development means for the residents of Uzbekistan
In recent years, the accessibility of financial services has increased significantly, but it is still too early to talk about the completion of this work. As of the beginning of 2026, nearly 70 million bank cards have been issued in the country, and the volume of digital payments continues to set new records almost every quarter. However, having a bank card does not yet mean full financial engagement. Many cardholders still primarily use them mainly for cash withdrawals at ATMs.
For us, a much more important indicator is how much people are transitioning from simple cash withdrawals to actively using digital financial services: paying for goods and services, making transfers, using savings products, microcredit, and other operations.
This is exactly where FinTech can play a key role. It goes where the people are: into mobile phones, into regions outside of Tashkent, into those segments of the economy that traditional banks have long largely ignored.
The development of BNPL services (“buy now, pay later”), embedded lending, and agency banking through digital platforms — marketplaces, microfinance organizations, and payment applications — allows reaching an audience that the classic branch network of banks often simply did not reach.
Our task as a regulator is to ensure that the expansion of financial accessibility does not come at the expense of consumer protection. For this, licensing, transparent disclosure requirements, and effective supervision of lending practices are necessary, especially when it comes to the most vulnerable categories of the population.
What FinTech in Uzbekistan will look like by 2030
By 2030, we expect to form a mature and competitive FinTech ecosystem. We anticipate that no less than 200 licensed FinTech companies will be operating in the country, the open banking ecosystem will function fully, and annually 15 to 20 Uzbek FinTech startups will be able to successfully enter international markets. Over the five-year period, the total volume of foreign investment in the industry should reach $1 billion.
An Innovation Hub will begin to function fully within the Central Bank, which will not only support innovative projects but also implement programs for compensating training costs, as well as provide a clear path from testing solutions in the regulatory “sandbox” to their commercial implementation.
We also expect that the volume of Islamic finance assets, which according to the latest estimates is about $1.1 billion, will at least double as a full regulatory framework for Islamic banking is formed.
Another important area is the digitization of money transfers. In 2025, their volume reached $18.9 billion, and we expect that an increasing share of these transactions will be carried out in digital format. In cases where this is permissible under legislation and does not contradict requirements for consumer protection, anti-money laundering, and ensuring financial stability, opportunities for using digital assets and blockchain technologies for cross-border transfers will also be explored.
This August, the Silk Road Finance and Technology Forum will take place in Tashkent. It is there that this agenda will be presented for the first time to such a wide international audience — regulators, investors, and business representatives from Central Asian countries, Gulf states, and other regions of the world.
Ultimately, our strategy is not aimed at achieving individual quantitative indicators. The main task is to create a financial sector that will be competitive at the regional level, will provide high-quality and accessible financial services to the citizens of Uzbekistan regardless of their income levels, and will be able to export its own technologies, products, and expertise beyond the country.
The Tech on Telegram Follow The Tech on Telegram
Keep up with the latest technology and startup news.
Related reading

More from this author

Article Useful
How to protect your accounts from hacking: 8 settings you should check today
The Tech

Article Useful
500 Global: How the Accelerator Works and Who Can Receive Investments
The Tech

Article Interviews
Game Development in Central Asia: Arkady Moldavski on Developing Reverb and the Growth of the Industry
The Tech

Article Useful
Google, Tesla, BlackRock, and the IMF: Where to Apply for an Internship in Fall 2026
The Tech

News IT
Tesla unveiled the flying electric car Roadster
The Tech

News IT
Intero Biosystems startup won the Startup Battlefield at TechCrunch Disrupt 2026
The Tech