Why a successful IT project is not yet a successful investment
Companies know how to implement ERP, CRM, and AI, but rarely check whether these projects have created real value. The author of The Tech, enterprise architect Laura Salamat, discusses the Cost-Effect-Value model.
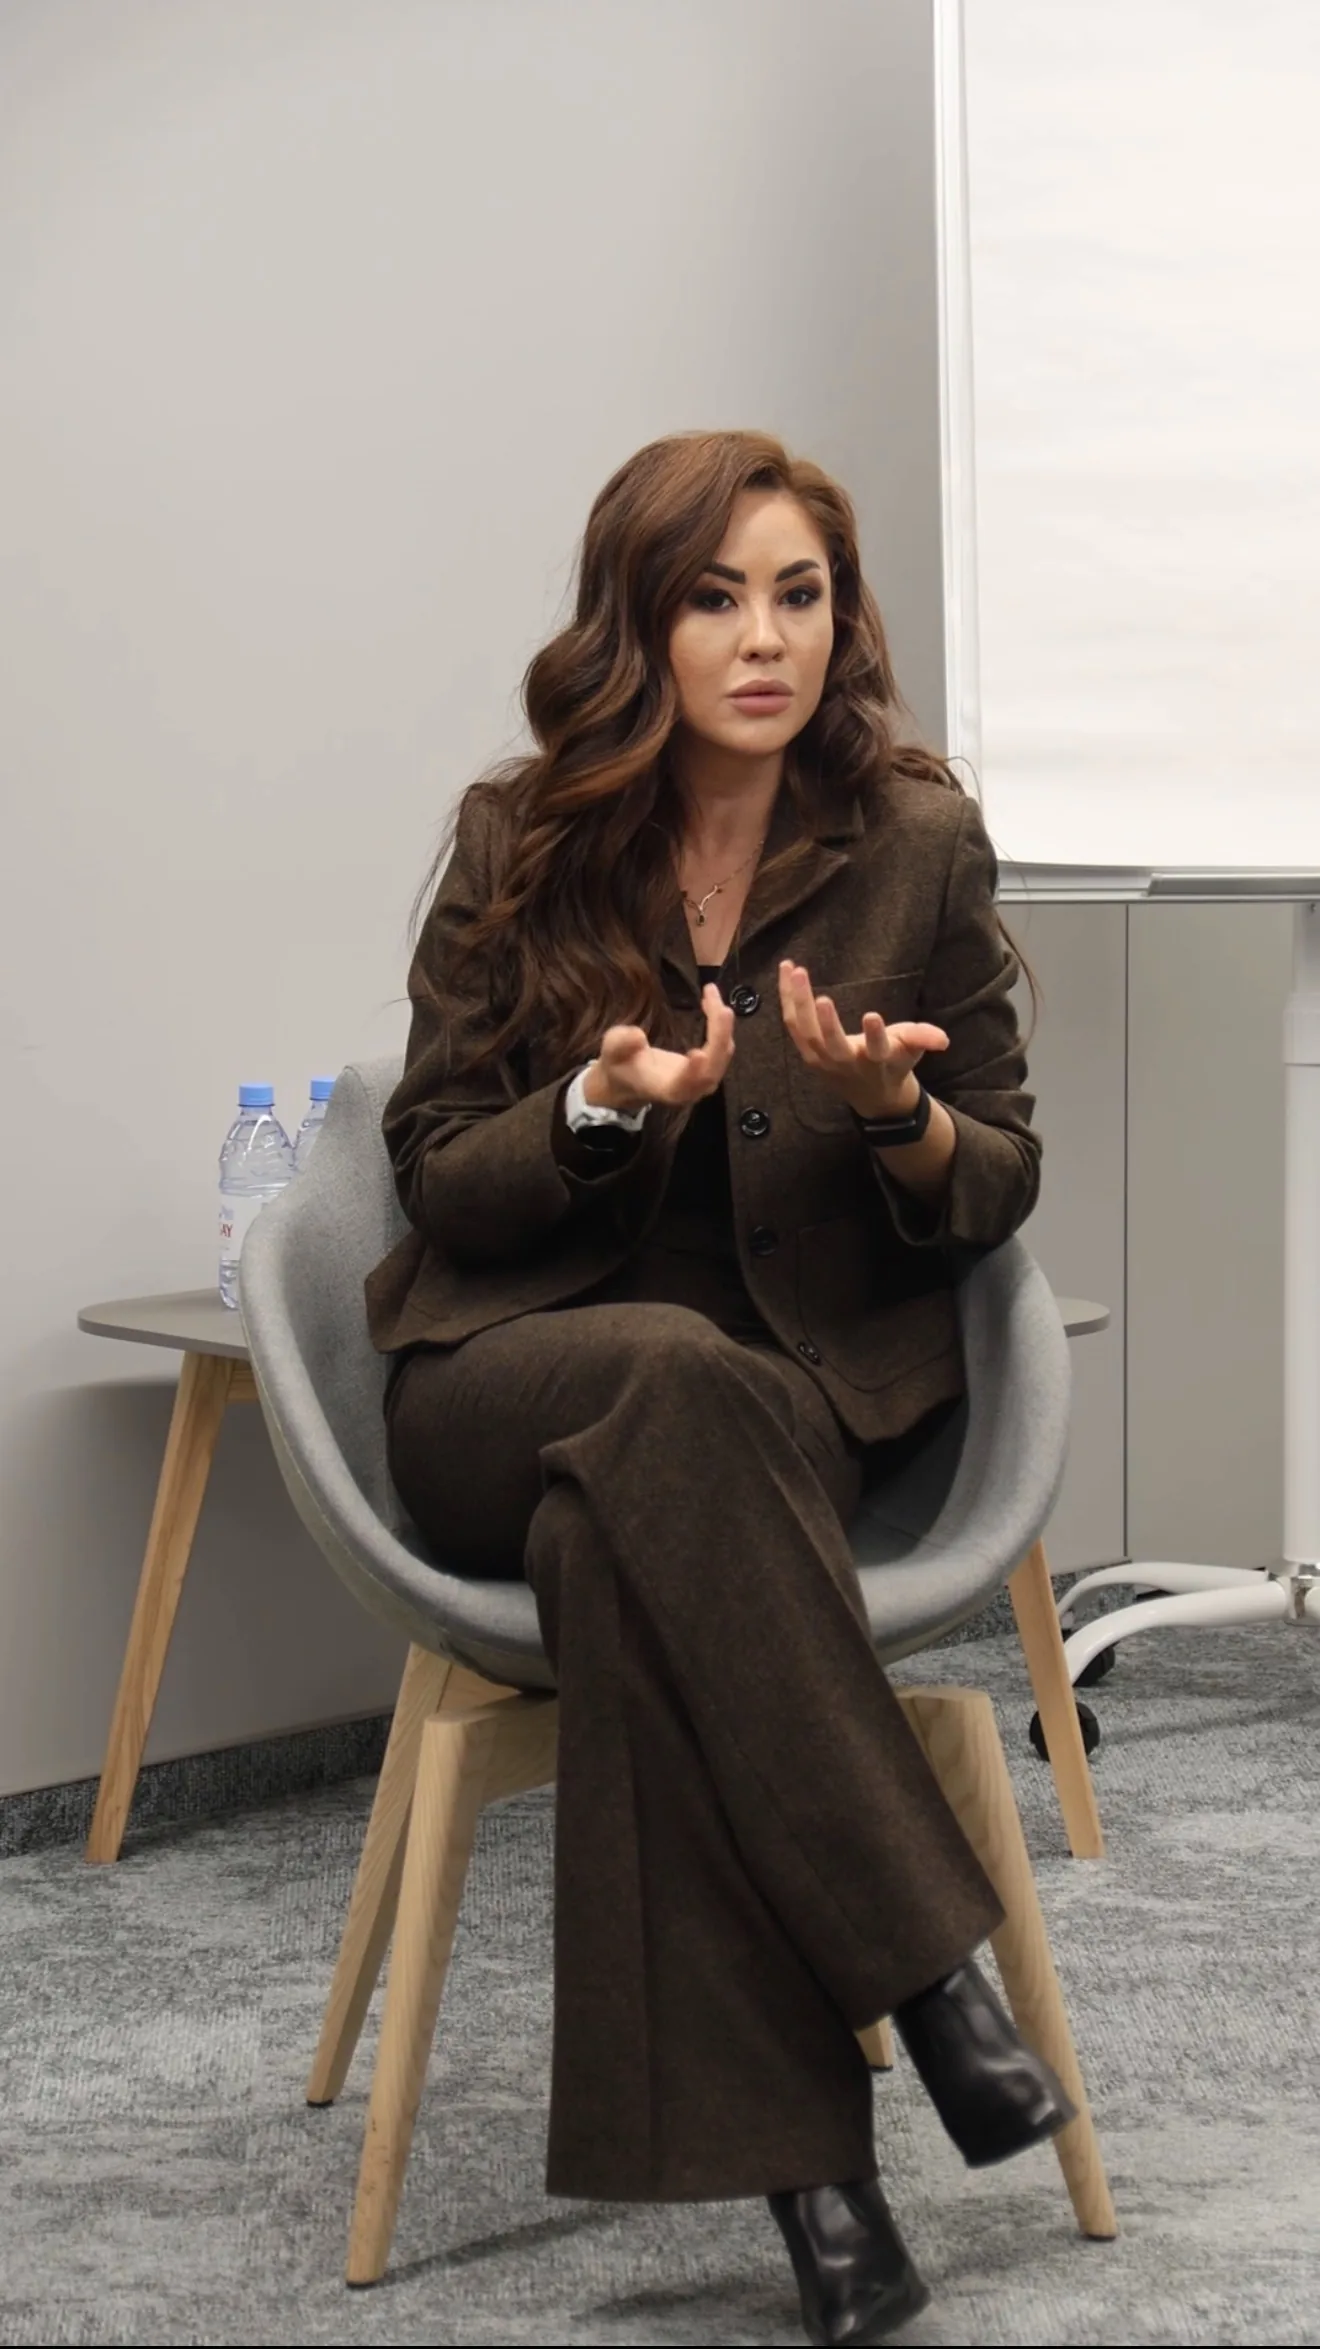
Laura Salamat, city — Almaty, Enterprise Architect, co-founder of the IT Architects Community of Kazakhstan, co-founder of Women in Tech Kazakhstan, CDTO at the Public Foundation “NNEF”
When a company launches a digital initiative, it almost always answers the same questions: what to automate, which solution to choose, how much it will cost, who is the executor, and what is the deadline. But there is a question that is asked significantly less often, although it is precisely this one that determines the success of any digital initiative.
What value should it create
For evaluating digital initiatives, there are business cases, financial models, ROI, NPV, payback period, and other tools. However, most of them assess only individual aspects of the project: implementation cost, budget adherence, timelines, or expected financial results. At the same time, they do not answer the main question — what value the digital investment creates for the business throughout its entire lifecycle.
This is why many companies still struggle with the objective assessment of digital investments. The problem is not a lack of competencies. Today, large organizations know how to manage complex digitalization programs, implement new technologies, and successfully execute large-scale projects. But after budget approval, they rarely ask the question: did these investments really create value for the business?
In my opinion, this is one of the main limitations of modern digital transformation. We have learned to professionally manage projects, but we have not yet learned to manage digital investments. Today, digital transformation needs a new management culture, a culture in which the object of management is not the project and not even the digital product, but the value they create for the business.
When a digital investment turns into a digital project
When a company decides to implement an ERP, CRM, data platform, AI, or any other digital solution, it invests not in the software product itself, but in expectations. In the expectation that processes will become faster, operational costs will decrease, data quality will improve, employees will stop wasting time on routine operations, and management decisions will be made faster and more accurately. These expectations are what give rise to a digital initiative. Essentially, this is an investment hypothesis — the expectation formulated before the start of the project regarding what changes the digital investment should bring and what value it should create for the business. And it is this hypothesis that should accompany the investment throughout its entire lifecycle. After all, it is for the confirmation of this hypothesis that the company makes the investment decision, but in practice, the opposite happens.
After budget approval, the company gradually stops managing the investment and starts managing the project. The focus shifts to solution architecture, functional requirements, timelines, budget, integrations, testing, data migration, and system commissioning. All of this is indeed important, as it is impossible to implement a digital initiative without quality project management; however, this is exactly where the key management error occurs.
A digital investment subtly turns into a digital project
A similar situation arose in a project where I participated in building an economic model and calculating the total cost of ownership for a portfolio of several dozen information systems. The cost of these systems was initially measured by the sum of contracts with contractors, a figure that is understandable and documented. But a contract fixes the cost of performing work, not the cost of owning the system. This is a category of project management, not an investment metric. The full calculation, which included the cost of internal personnel, infrastructure, information security, and subsequent changes, resulted in a figure twice as high as the original one. The cost of internal employees, an item usually not classified as expenses because “they are already on the payroll,” turned out to be comparable to the entire contractual budget.
From that moment on, the main objects of management become timelines, budget, scope of work, and successful project completion. At the same time, the initial investment hypothesis gradually recedes into the background. Companies begin to evaluate how successfully the project was implemented, instead of checking whether the expectations for which the investment was approved were confirmed. This is why a successful project does not always mean a successful digital investment.
A project is a way to implement changes; an investment is a decision to create future value.
The economics of digital investments: Cost-Effect-Value model, CEV
If a digital investment is viewed as an investment hypothesis, the company must have the ability to confirm or refute it based on objective data. This creates a need for a new economic logic, since existing approaches assess individual characteristics of a digital initiative but do not allow tracing the path from the investment decision to the created value.
Similar tasks are addressed by methodologies such as Val IT or the benefits realization management approach. Both focus on the link between IT investments and business value. But in practice, they often remain at the level of high-level corporate methodology and rarely reach the specific portfolio of systems and figures by which the budget is calculated each year.
The economics of a digital investment should be built on three sequentially linked levels. First, the company understands the cost of the investment — Cost, then evaluates the changes it caused — Effect, and only then determines what value these changes created for the business — Value. This sequence lies at the heart of the CEV principle.
Cost answers the question not about the cost of the project, but about the cost of the investment itself throughout its entire lifecycle. The calculation should include not only development or implementation costs, but also expenses for licenses, infrastructure, support, integrations, development, information security, user training, and subsequent modernization. At this stage, it becomes possible to compare different implementation scenarios for the investment and understand its real cost, not just the initial project budget.
Effect reflects the changes that occurred due to the investment. Here, it is no longer sufficient to measure the number of users, the volume of implemented functionality, or the percentage of automation. It is much more important to understand whether the cost of business processes has changed, whether the time to perform operations has decreased, whether the number of errors has reduced, whether resources have been freed up, data quality has improved, or operational risks have been reduced.
Changes acquire meaning only when they lead to the creation of Value, value for the business. It can be expressed in reduced operational costs, prevention of future expenses, increased productivity, the ability to scale without a proportional increase in resources, improved quality of management decisions, or the emergence of new business opportunities.
Returning to the same portfolio of systems, the Cost-Effect-Value chain was completed there. Based on the full, rather than contractual, cost, a target state scenario was built, and over a five-year horizon with discounting, NPV, IRR, and the payback period for the transition were calculated. NPV turned out to be positive, IRR exceeded the discount rate, and the investment paid back within the calculation horizon, meaning the project’s economics were confirmed by objective indicators, not by assumptions about its success. Moreover, the conclusion would have been the opposite if Cost were still calculated only based on contractual payments, since without taking into account the total cost of ownership, the very basis for calculating NPV and IRR would have been distorted.
This approach represents a single causal chain, in which the cost of a digital investment leads to changes, changes form value, and value allows confirming or refuting the initial investment hypothesis.
The economics of digital investments is not an attempt to replace ROI, NPV, or other financial indicators. On the contrary, it unifies them into a single management logic, allowing one to trace the path of a digital investment from the initial hypothesis to confirmed value. The next stage of digital transformation maturity is already associated not with the implementation of new technologies or the appearance of new digital products, but with a change in the approach to investment management itself. As long as the object of management remains the project, companies will strive to complete implementation on time, stay within budget, and deliver the planned functionality. But as soon as the object of management becomes the digital investment, the success criteria also change. The main thing is no longer the fact of implementing a digital product, but the confirmed value it has created for the business.
This transition is the next stage of digital transformation maturity. A new culture of managing digital investments begins at the moment when the object of management is not the fact of implementing a digital solution, but the confirmed value it creates for the business.
The Tech on Telegram Follow The Tech on Telegram
Keep up with the latest technology and startup news.
Related reading




More from this author

Article Useful
How to protect your accounts from hacking: 8 settings you should check today
The Tech

Article Useful
500 Global: How the Accelerator Works and Who Can Receive Investments
The Tech

Article Interviews
Game Development in Central Asia: Arkady Moldavski on Developing Reverb and the Growth of the Industry
The Tech

Article Useful
Google, Tesla, BlackRock, and the IMF: Where to Apply for an Internship in Fall 2026
The Tech

News IT
Tesla unveiled the flying electric car Roadster
The Tech

News IT
Intero Biosystems startup won the Startup Battlefield at TechCrunch Disrupt 2026
The Tech